What makes sustainability particularly complex, and compelling, is that it is not a single strategy or solution but a balance of tradeoffs: natural versus synthetic, local versus scalable, transparency versus simplicity, and speed to market versus long‑term impact. As regulatory scrutiny tightens and consumer expectations mature, sustainability is evolving from a compliance exercise or marketing differentiator into a strategic capability that shapes R&D priorities, partnerships, investment decisions, and ultimately competitive advantage.
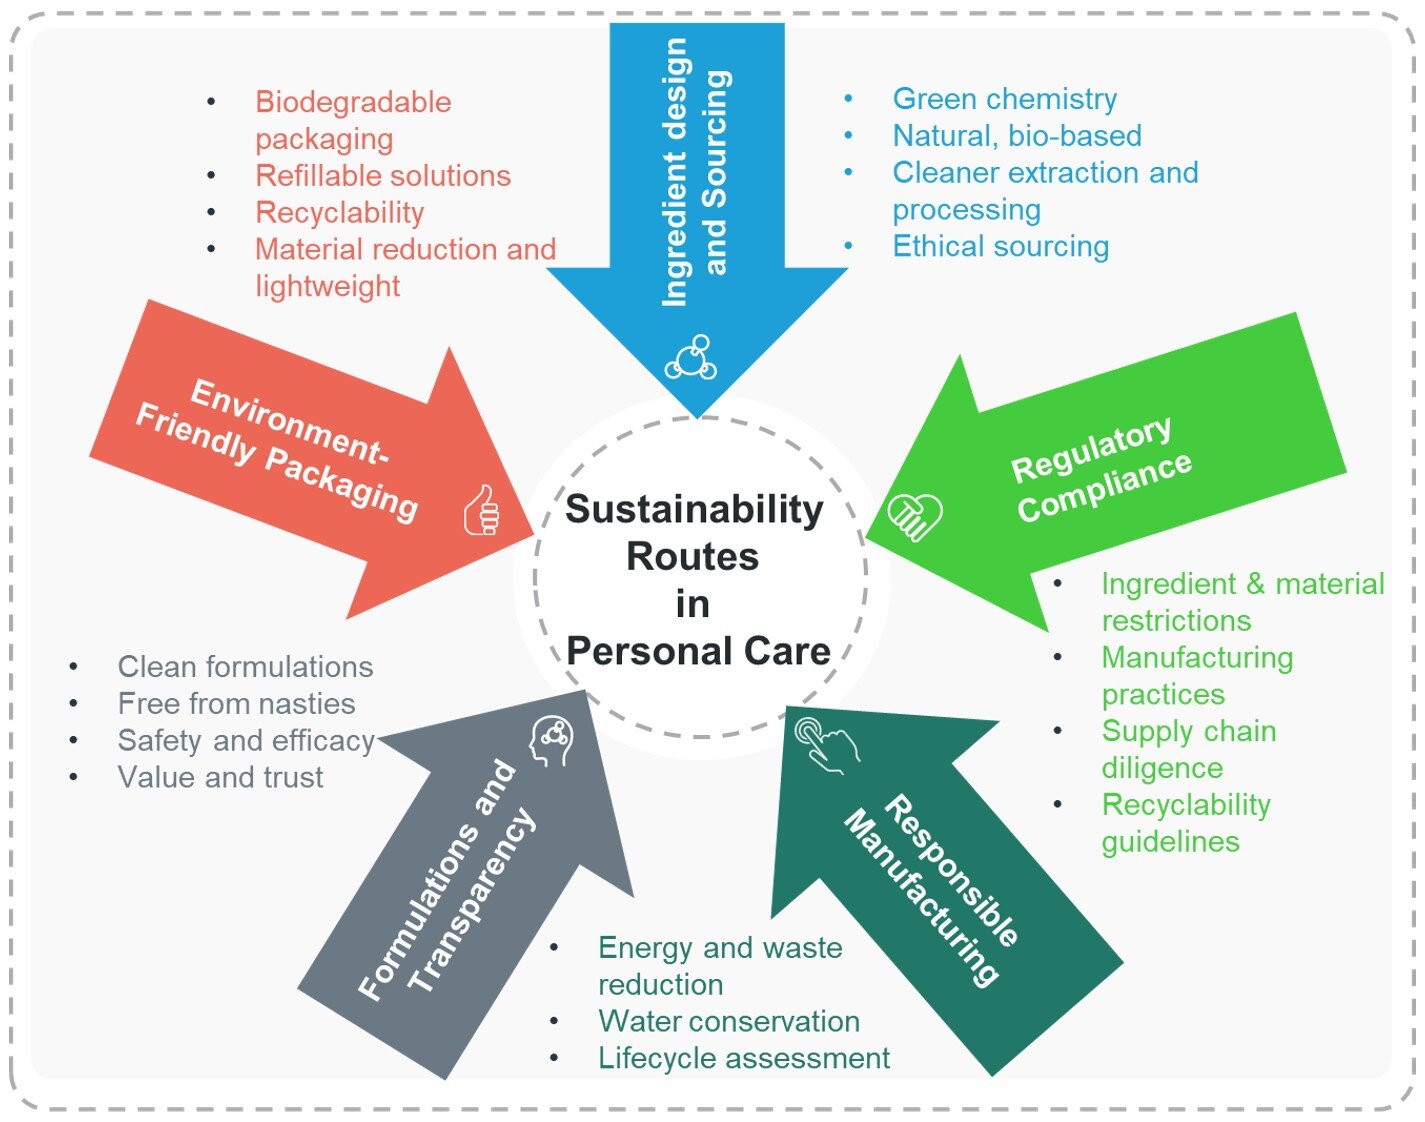
Sustainability in personal care does not follow a single pathway. Instead, it is shaped by varying regulatory expectations, regional market priorities, technical capabilities, supply‑chain maturity, and consumer perceptions. Companies’ ability to act is further influenced by formulation complexity, manufacturing assets, access to alternative materials, and innovation readiness. As a result, rather than being a fixed concept, sustainability becomes a set of interconnected approaches that play out differently across markets, product categories, and value‑chain roles.
- Plant‑based emollients such as shea butter, jojoba oil, and sugarcane‑derived squalane are increasingly used in place of petrochemical oils and silicones to deliver moisturization and skin feel while relying on renewable feedstocks.
- Synthetic surfactants such as SLES are being complemented or replaced by naturally derived options such as coco‑glucoside and plant oil‑based betaines that offer gentler cleansing profiles.
- Natural thickening and structuring agents—including xanthan gum, cellulose derivatives, and starch‑based polymers—are being designed to replace synthetic rheology modifiers such as carbomers.
- Plant oil‑based esters and biosurfactants developed from coconut, palm alternatives, or sugar chemistry are used to lower carbon footprint and improve biodegradability.
- Biobased polymers and styling agents derived from starches or cellulose are emerging as alternatives to synthetic acrylates with improved end‑of‑life profiles.
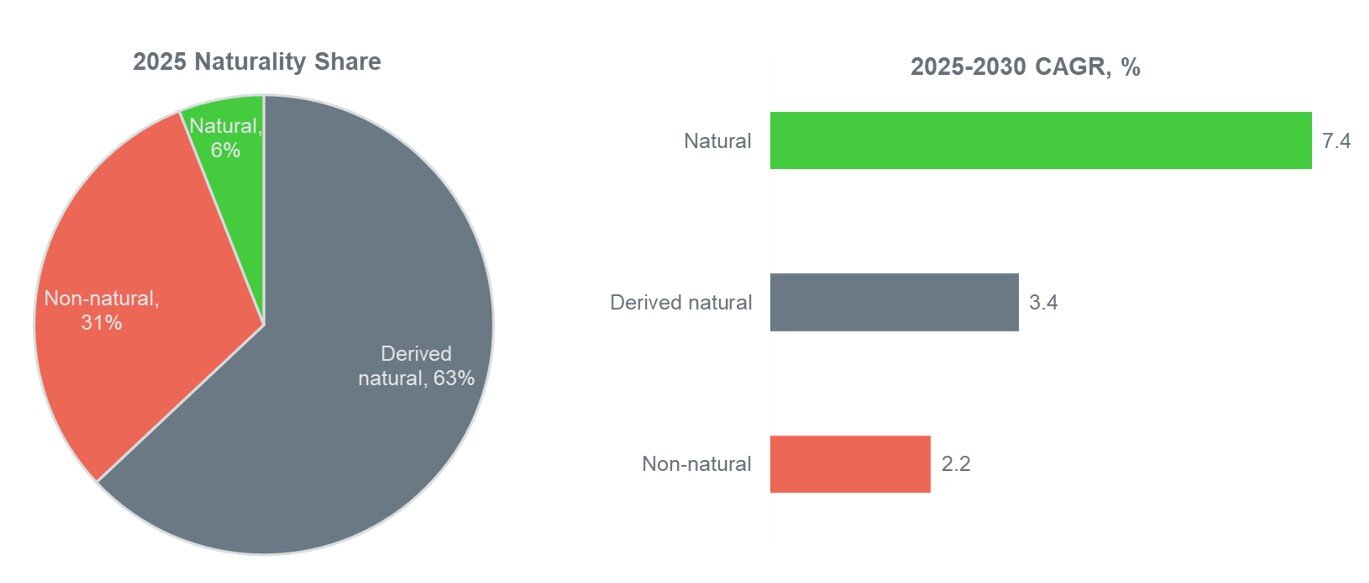
Despite these advances, purely natural ingredients still represent a relatively small share of global personal care formulations due to cost, stability, supply variability, and sensory limitations. Derived‑natural ingredients therefore remain the mainstream solution, acting as a scalable bridge between naturality and performance. As derived‑natural becomes the baseline, brands—particularly in premium, sensitive skin, baby care, and clean‑label segments—are increasingly pushing further toward fully natural ingredient systems.
- In Europe and North America, sustainability expectations and regulatory pressures are pushing brands to ensure fair‑labor compliance and traceability for raw materials such as mica and palm‑derived ingredients, supported by certification frameworks and initiatives such as the EU Deforestation Regulation.
- In Africa, ethical sourcing initiatives around shea butter and botanical oils increasingly focus on fair compensation and the economic empowerment of women‑led cooperatives while safeguarding biodiversity.
- Across Asia‑Pacific, rapid market growth is elevating expectations for responsibly sourced natural ingredients, prompting brands to adopt localized sourcing models, improve transparency, and build supplier partnerships aligned with regional sustainability standards.
Beyond sourcing ethics, extraction methods shape the sustainability profile of ingredients, particularly botanical actives. Supercritical CO₂ extraction is widely used for sensitive botanicals as it avoids toxic solvents while preserving bioactive compounds. Water‑based, enzymatic, and fermentation‑assisted extraction methods are gaining traction due to lower energy intensity, improved selectivity, and enhanced bioavailability.
- Energy efficiency is being improved through measures such as variable-speed drives, heat recovery systems, insulation, and automation, which help lower operational costs and emissions.
- In emulsions manufacturing, the shift toward cold‑process or low‑temperature emulsification reduces heating and cooling energy while shortening batch times.
- For active ingredients, manufacturers are adopting pre‑standardized or concentrated formats produced through optimized extraction or fermentation, minimizing off‑spec material, reprocessing, and waste.
- Simplified and multifunctional surfactant systems further support process efficiency by reducing formulation steps, water use, and clean‑in‑place requirements.
Life cycle assessment (LCA) is reinforcing these manufacturing shifts. By evaluating carbon emissions, water use, and waste generation across the value chain, LCA supports a move beyond single‑attribute sustainability claims toward more holistic, data‑driven decision‑making.
- Shift toward recyclable and circular materials: Cosmetic brands are increasingly using PET, HDPE, aluminum, and glass, which support established recycling streams and closed‑loop systems. To improve real‑world recyclability, many are moving toward mono‑material designs and incorporating post‑consumer recycled (PCR) content.
- Refillable and reduced material formats: Refill systems are gaining traction as a way to reduce packaging waste. Lancôme’s refillable La Vie Est Belle fragrance allows a 100 ml refill to replace two 50 ml bottles, cutting 73% of glass, 66% of plastic, and 61% of cardboard. The Body Shop’s in‑store refill stations have prevented over 500,000 plastic bottles in one year, while Dove’s refillable deodorant system combines a durable metal case with plastic refills to reduce virgin plastic use at scale.
- Packaging enabling formulation innovation: Advanced solutions such as airless packaging and protective delivery systems are supporting formulation trends such as preservative‑free and low‑preservative products by reducing contamination risk and improving product stability.
- Innovative alternatives and lightweighting: Beyond conventional materials, brands are exploring light‑weighted packaging, biobased materials, coated paper solutions, and alternative barrier technologies to further reduce plastic use and transportation‑related emissions.
- Packaging‑led preservation: Technologies such as airless packaging, barrier‑enhanced containers, and controlled‑dose delivery systems reduce product exposure to air and microbial contamination during use, improving stability and shelf life.
By integrating packaging innovation into broader sustainability strategies, brands can significantly reduce environmental impact while maintaining product performance, safety, and consumer appeal.
- In the European Union, the EU Cosmetics Regulation requires safety assessments, restricted substance control, and clear labeling, while packaging laws promote recyclable materials and waste reduction.
- In the United Kingdom, UK Cosmetics Regulations mirror many EU standards post-Brexit.
- In the United States, the FDA oversees cosmetics safety and labeling under the Modernization of Cosmetics Regulation Act (MoCRA), while states such as California have stricter rules on chemicals and packaging waste.
- In India, the personal care sector is governed by the Drugs and Cosmetics Act, BIS standards, and Plastic Waste Management Rules, which include extended producer responsibility (EPR) requirements.
- Chinese regulations have evolved to ease some animal testing requirements for general cosmetics while maintaining strict registration and ingredient compliance.
- Markets such as Japan and South Korea maintain strong product safety, labeling, and functional claim regulations.
- Across Latin America, markets such as Brazil (ANVISA) and Mexico enforce product registration and labeling requirements.
- In the Middle East, markets such as United Arab Emirates and Saudi Arabia emphasize halal compliance, import registration, and Gulf standards.
- The ASEAN Cosmetic Directive harmonizes regulations across Singapore, Thailand, Indonesia, and Malaysia, among other markets.
The European Union’s regulation of cyclomethicones illustrates how environmental concerns are influencing ingredient choices in personal care. Cyclic silicones such as D5 and D6, long valued for their sensorial benefits, are being restricted due to persistence and bioaccumulation concerns, prompting brands to reassess silicone use. This has accelerated interest in alternative sensorial systems, including ester blends, alkanes, and modified silicone technologies that can partially replicate performance. Beyond reformulation, the regulation is also driving broader sustainability improvements in synthetic ingredient manufacturing, encouraging greater process efficiency and lower‑impact production models.
Another key compliance area is the use of environmental and ethical claims. Terms such as natural, organic, biodegradable, vegan, and cruelty-free must be backed by reliable certifications, testing data, or third-party verification. Regulators across the world are dialing up the scrutiny of misleading claims to prevent greenwashing and protect consumers. Brands must ensure that marketing messages accurately reflect the product’s sustainability credentials.
Companies that proactively align with these evolving regulations can reduce legal risks, improve brand credibility, and meet growing consumer demand for responsible personal care products. In today’s market, regulatory compliance is both a legal necessity and a strategic advantage.
References and notes
- Kline + Company, Personal Care Ingredients: Market Analysis and Opportunities, 2025
- Kline + Company, Specialty Actives in Personal Care: Global Market Analysis and Opportunities, 2024
Explore the article in the digital edition
Korean Cosmetic Ingredients: How Korea Turned Ingredients into Brand P...
Plant-derived Extracellular Vesicles as emerging biological delivery v...
PEER REVIEWED – Plant-Derived Extracellular Vesicles Improve Sca...
The Longevity Shift: How the Pursuit of Healthspan Is Reshaping Beauty...
K-Beauty 2.0: Evolving Through Science, Biotechnology, and Data
Shades of Protection: Rethinking the Future of EU Sunscreen Regulation

Beyond the SPF Number: Why Microbiome Compatibility Must Become the Ne...

Consumer Perspective: What Indie Brands Get Right About Consumer Psych...